Somewhere right now, a fintech, electronic money institution, or microfinance institution is eighteen months into a “12-month” digital bank launch.
The pitch deck promised speed. The reality is a procession of vendor calls, compliance sign-offs, and integration tickets, each one quietly pushing go-live into another quarter.
This is not a talent problem. It is not a budget problem. It is a platform problem. And it is one of the biggest reasons promising digital banking propositions lose momentum before they reach a single customer.
The advantage was supposed to be speed. Instead, the launch consumes the runway.
02Where the 12 to 18 Months Actually Goes
Most digital bank launches follow a familiar, and preventable, sequence.
Months 1 to 4
Core selection and contracting
Legacy vendors still run procurement like enterprise software from a decade ago: long RFP cycles, rigid licensing, and implementation partners working around technology that was never designed for cloud-native delivery.
Months 4 to 9
Integration becomes the project
Payments rails, KYC providers, card networks, and open finance APIs each demand a separate connection. What should be product configuration turns into multi-team engineering.
Months 8 to 14
Compliance gets retrofitted
Regulatory reporting, AML controls, and risk frameworks arrive after the core is “mostly done.” Every late gap becomes a schedule slip instead of an early design decision.
Months 12 to 18
Testing, remediation, and a new launch date
By the time the system works end to end, the original business case has aged, competitors have moved, and the team is exhausted before day one.
03The Root Cause Is Not the Vendor List. It Is the Sequence.
Traditional core banking programmes treat compliance and integration as additions: first build the core, then connect the ecosystem, then prove that the result satisfies regulators.
That order creates expensive rework. A late compliance requirement can affect data models, workflows, customer journeys, reporting, and third-party integrations all at once.
The Critical Shift
Compliance and connectivity should not surround the core. They should be designed into it from day one.
04What Changes With a Cloud-Native, Compliance-Ready Core
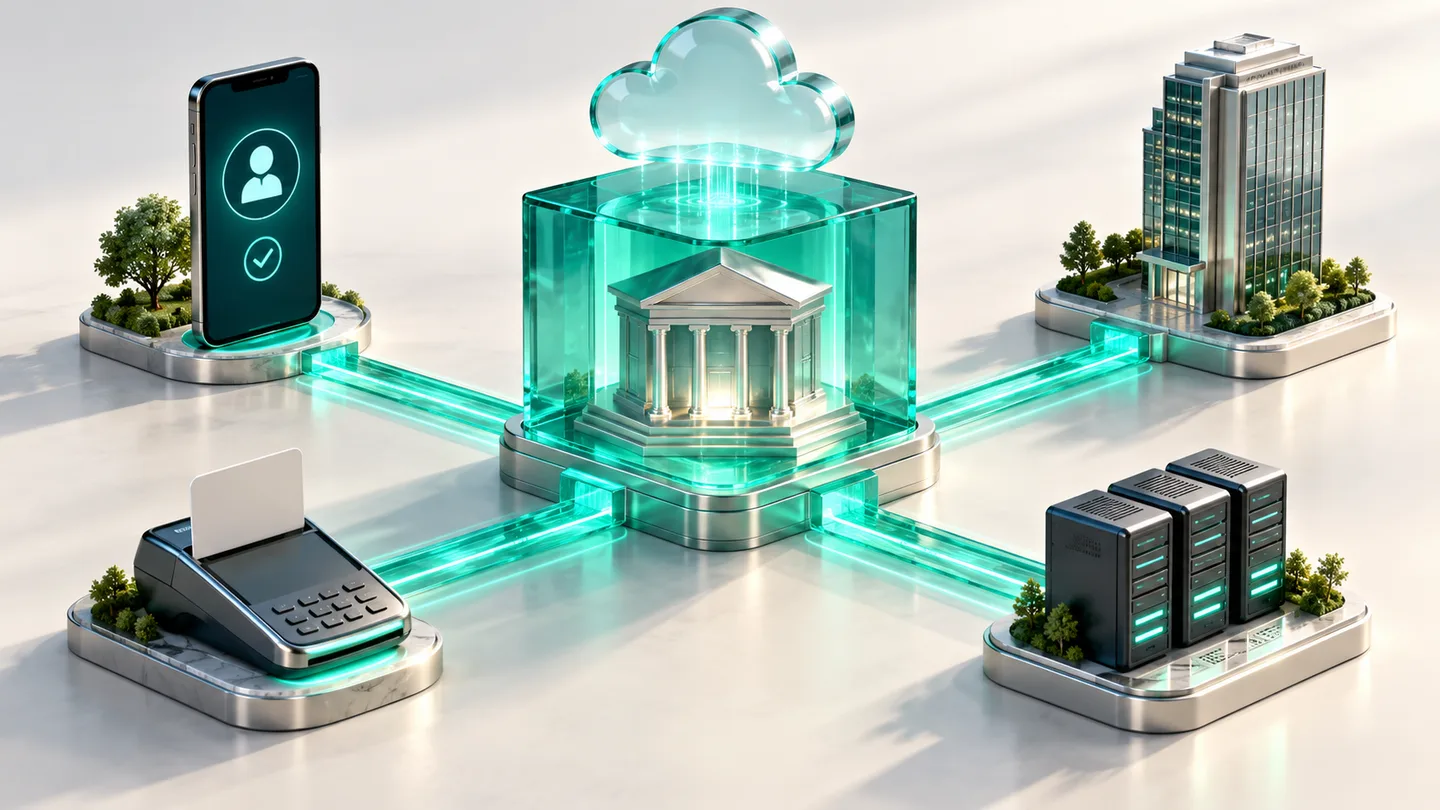
NeuroBank, Neuronix's Digital Financial Services platform, is built to close this gap. It gives financial institutions, EMIs, MFIs, and fintechs a full-spectrum foundation for launching digital banking across retail, corporate, and agency channels.
Core Banking, Compliance AI, Alt Risk, Open Finance, and Corporate Banking capabilities work as one platform, not as five separate programmes forced to meet at the finish line.
01
Integration shrinks from a project to a configuration
An API-first architecture makes it possible to enable payments, KYC, cards, and open finance connections without engineering every relationship from scratch.
02
Compliance moves from a late gate to a built-in layer
AI-driven compliance and risk capabilities operate natively within the platform, so regulatory readiness advances with the product, not behind it.
03
Go-live is governed by readiness, not vendor cycles
When the core, compliance layer, and risk engine share one foundation, the burden of testing, reconciliation, and remediation falls dramatically.
05What This Means for Your Launch Timeline
Institutions choosing legacy cores are often committing to the same 12-to-18-month arc: integrate first, add compliance later, and accept slippage at every handoff.
A cloud-native, compliance-ready core compresses that journey because it removes much of the work that made the old timeline long in the first place.
The gap between “board approved” and “customers onboarded” is an architecture gap.
06The Bottom Line
A modern digital banking platform should do more than help you launch faster. It should help you launch with the controls, connectivity, and flexibility needed to scale, without rebuilding the foundation after go-live.
If your launch is still measured in quarters instead of weeks, the right question is no longer, “How do we accelerate the project?” It is, “Why are we still building around a core that creates the delay?”
See What a Compliance-Ready Core Looks Like.
Explore NeuroBank and discover how a modern banking foundation can change your path from approval to launch.